The Lebanese government’s fiscal recovery in recent years would be something to applaud if it weren’t being paid for by the people least able to afford it and protecting those least in need of protection.
When Parliament opens its budget session next month, the government is expected to be running a fourth consecutive year of surplus, meaning it’s bringing in more money than it spends.
This is an astounding outcome given the Israeli bombing and occupation Lebanon has endured since 2023, which was preceded by four years of financial and political crises, the Beirut port explosion, and the COVID-19 pandemic.
Meanwhile, Lebanese society is unraveling in real time: more than 1 million people will likely need food assistance into 2027; almost a third of private-sector workers are no longer employed following the 2026 war; and almost 730,000 Lebanese nationals have emigrated since 2020.
In light of these statistics, a question arises: why is Lebanon’s social protection system failing to protect its people? The answer lies in an old and unequal insurance architecture, the elevation of targeted cash assistance into the state’s main anti-poverty instrument, and an austerity regime that claims resources are scarce for social protection as it mobilizes billions to manage bank losses.
Protection for the Few
On the eve of the crisis, Lebanon relied on six major public insurance funds. Private-sector workers and employers contributed to the National Social Security Fund, while separate state-backed schemes covered civil servants and the security forces. These systems financed healthcare, family allowances, and lump-sum end-of-service indemnities. Access was conditional on formal employment, leaving 40% of Lebanese without coverage.
Around 60% of government social-protection spending went to public-sector end-of-service benefits, benefiting just 2.5% of the population.
In 2019, commercial banks froze deposits, including those of insurance funds. As the Lebanese Lira lost 98% of its value, much of the insurance funds’ savings depreciated as well. Moreover, while nominal spending on social protection increased as a share of the state budget from 2020-23, in real terms, due to currency collapse, this amounted to a 91% cut, dropping from an average of $6.6 billion a year before the crisis to $600 million a year from 2020-23. This cut came with the government already behind on its contributions to the NSSF.
As contributory protection collapsed, a residual poverty program moved to the center of social policy. The National Poverty Targeting Program, launched in 2011 with World Bank support, had reached 43,000 households before the crisis, roughly 4% of the population. After 2019, it was expanded and merged with the Emergency Social Safety Net, a World Bank-funded program created to respond to the crisis, forming what became the AMAN program.
AMAN is now the country’s principal instrument of social protection. It selects poor households via proxy means testing, using indicators such as whether a household owns a car or a refrigerator, and in global assessments has been shown to be highly inconsistent and unreliable at identifying those in need. This assessment is made even less accurate by Lebanon’s volatile context: high inflation and displacement decrease the accuracy of targeting.
The program provides a maximum of $145 per household per month, covering less than a third of the basic needs a family requires to survive. This sits uneasily with AMAN’s own stated goals, which include helping households exit poverty through gradual economic inclusion.
These programs are politically attractive precisely because they are cheaper and simpler than rebuilding social insurance.
A review by CAMEALEON, a coalition funded by the European Union and Norway and tasked with monitoring Lebanon’s cash assistance, reported in its final review that the assistance did not relieve households from poverty. The assistance was found to last under two weeks, with household debts reaccumulating as soon as the transfers end. It also found that AMAN’s targeting and delivery mechanisms leave many vulnerable households excluded or unable to access support. In other words, even the narrow safety net Lebanon has built does not reliably reach those it is supposed to protect. The Minister of Social Affairs, Haneen Sayed, who was central to the NPTP’s 2013 expansion during her tenure at the Bank, has rejected the coalition’s findings as distorting policy decisions, resting on limited evidence, and ideologically driven.
Cash assistance is useful to manage crises and transitory periods, as poor households cannot wait for structural reform. The problem arises when cash assistance is expected to become the backbone of Lebanon’s anti-poverty response when it can only be an emergency layer that sits on top of social insurance.
These programs are politically attractive precisely because they are cheaper and simpler than rebuilding social insurance. They allow governments and donors to administer poverty through a bounded, measurable program without tackling structural reforms such as resolving labor market distortions to restore social insurance, expanding public services, or taxing wealth to finance welfare.
Austerity for the many
The claim that the state simply lacks the resources to protect people becomes harder to sustain when looking at Lebanon’s wider fiscal policy. In 2025, the government recorded a surplus of 3.9% of GDP, and another surplus is projected in 2026 even as the economy contracts by 6.4% and inflation reaches 17.5%.
These surpluses are being generated through stronger tax collection alongside continued austerity. Government revenues reached $6.18 billion in 2025, with value-added tax and customs supplying 38.3% of the total and VAT receipts alone rising 49%, against expenditure of $4.74 billion, over half of which was personnel costs.
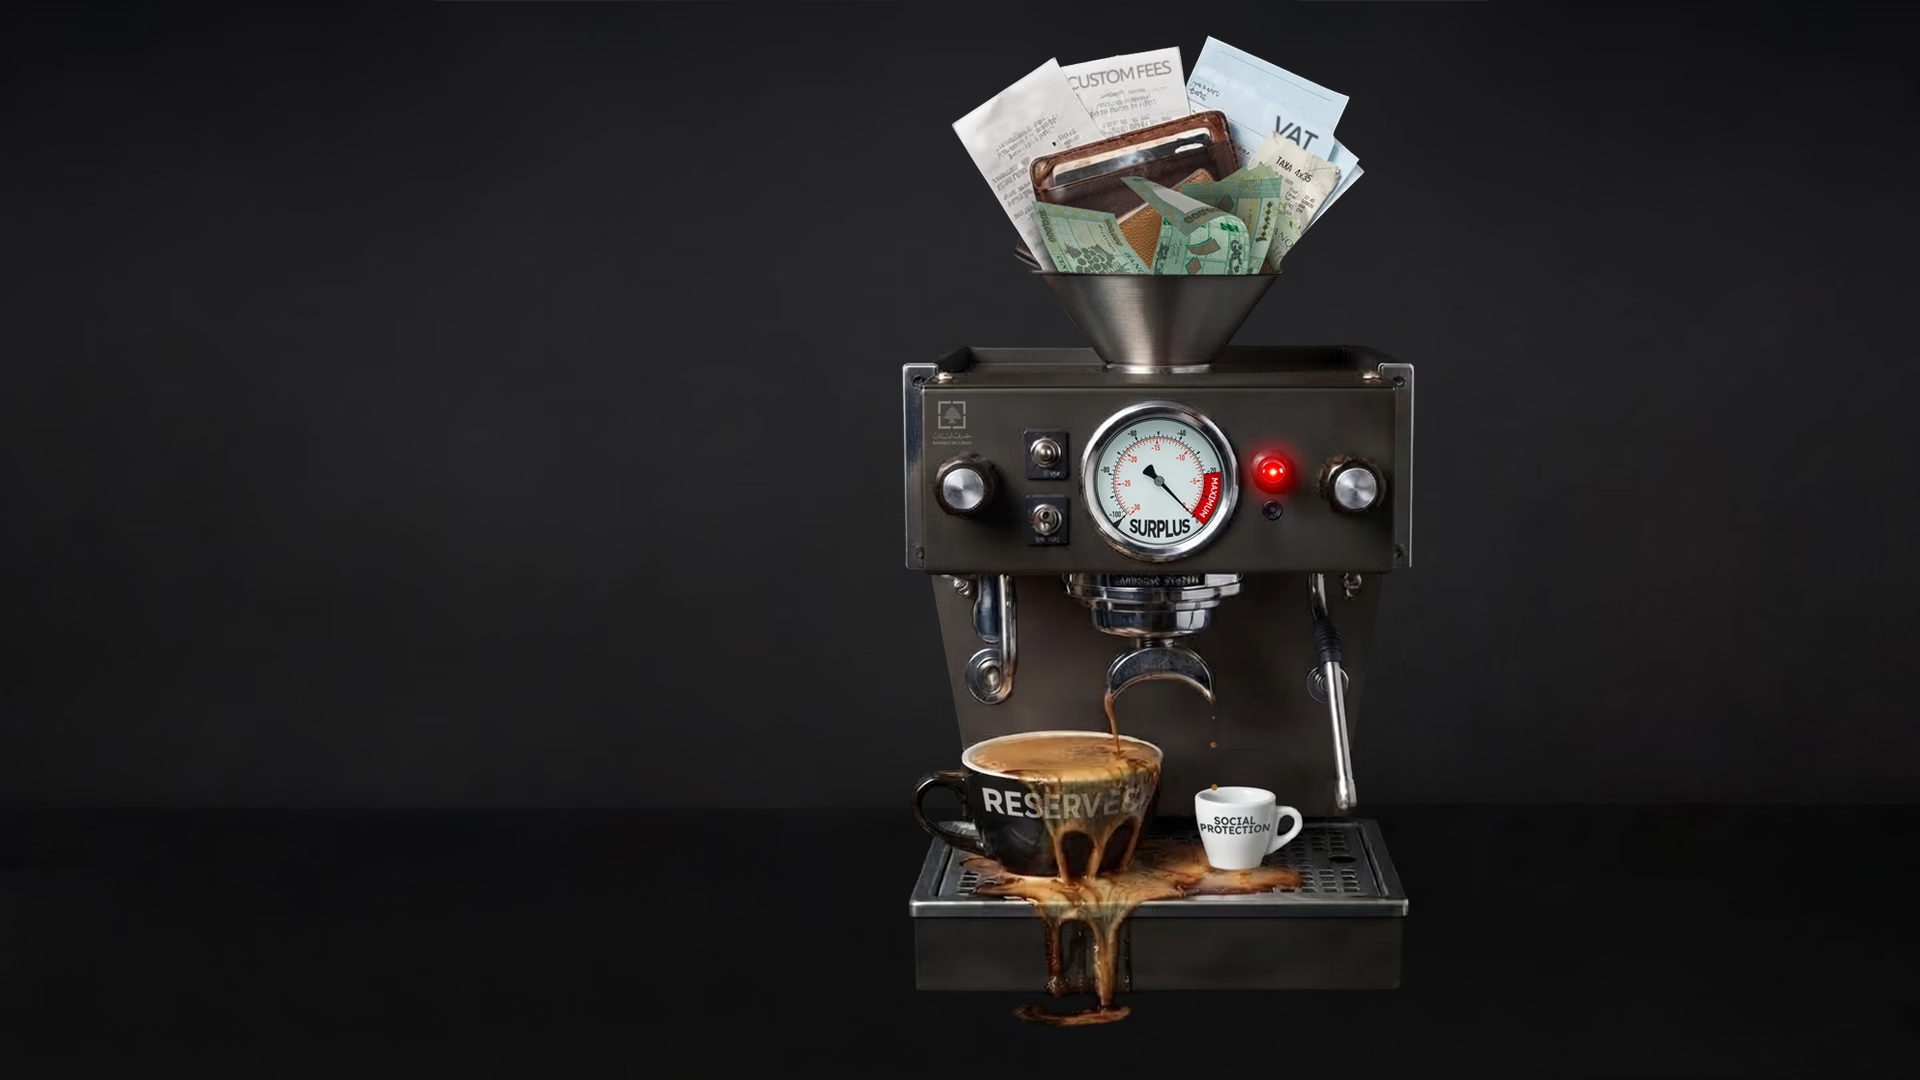
Throughout 2025, the central bank increased depositor payouts by 40% under Circular 158 and by 200% under Circular 166, with the program now repaying over $2.5 billion annually. That’s equivalent to half of everything the Lebanese state spends; however, it does not feature on the government’s budget. In March this year, cumulative payouts reached $6.1 billion, having gone to almost 580,000 depositors, half of whom have already closed their payout sub-accounts. BDL’s share of the payout in March was 88.2% versus the commercial banks’ 11.8%. If sustained, that would be a marked increase from the two-thirds share the BDL averaged over previous years of the payback scheme.
Lebanon can therefore mobilize billions to bail out the banks while it claims that $145 a month to poor households is what fiscal realism permits.
Every dollar the central bank pays reduces what commercial banks still owe their customers, without first writing down bank equity and forcing shareholders to absorb losses through an orderly restructuring, as required by the creditor hierarchy established under Lebanon’s Bank Resolution Law but still left unclear under the Financial Gap Law. In other words, BDL is running an effective bailout scheme in which taxes disproportionately drawn from average consumers socialize private banking losses without parliamentary oversight.
Lebanon can therefore mobilize billions to bail out the banks while it claims that $145 a month to poor households is what fiscal realism permits.
Protection, not poverty management
Better social protection cannot be reduced to increasing AMAN payments. Although their inadequacy can and must be corrected, cash transfer programs are by design incapable of providing lifecycle protection. Lebanon must restore and reform contributory insurance, protect people when they lose employment, and stop treating targeted assistance as a substitute for social rights.
Assistance programs must work alongside efforts to remedy the conditions producing poverty in the first place: mainly labor market distortions and the cost-of-living crisis. Confronting monopolistic pricing, regulating rents, tuition, and healthcare costs can increase households’ effective incomes at no direct cost to the treasury. Shifting the tax burden away from regressive taxes on labor and consumption toward wealth and profits is equally essential to increasing disposable incomes and financing stronger social protection.
None of this is compatible with shielding the banking sector’s shareholders from the losses they incurred. The financial gap cannot be closed by extracting from workers and consumers while preserving shareholder interests, only to borrow again to provide the poorest with inadequate relief.
In 2024, the International Labour Organization estimated that Lebanon can achieve basic universal social protection (cash benefits for children, disability, maternity, old-age, and unemployment) by spending 3.2% of its GDP, or $976 million. At 9.4% of GDP, it could also include basic universal health coverage, bringing the total cost to $2.9 billion.
The state can either protect the social order that produced the 2019 collapse, or the society that is still paying for it, but it cannot do both.
Scarcity as an obstacle to universal and rights-based social protection is inherently political: it justifies the state’s choice in deciding whose claims to honor. A country that can mobilize $2.5 billion a year to bail out its banks cannot present poverty management as its ultimate social ambition, especially when a comparable sum could provide everyone with basic protection. The state can either protect the social order that produced the 2019 collapse, or the society that is still paying for it, but it cannot do both.
The views expressed in this article are solely those of the author and do not necessarily reflect the views of BADIL | The Alternative Policy Institute or its editorial team.